
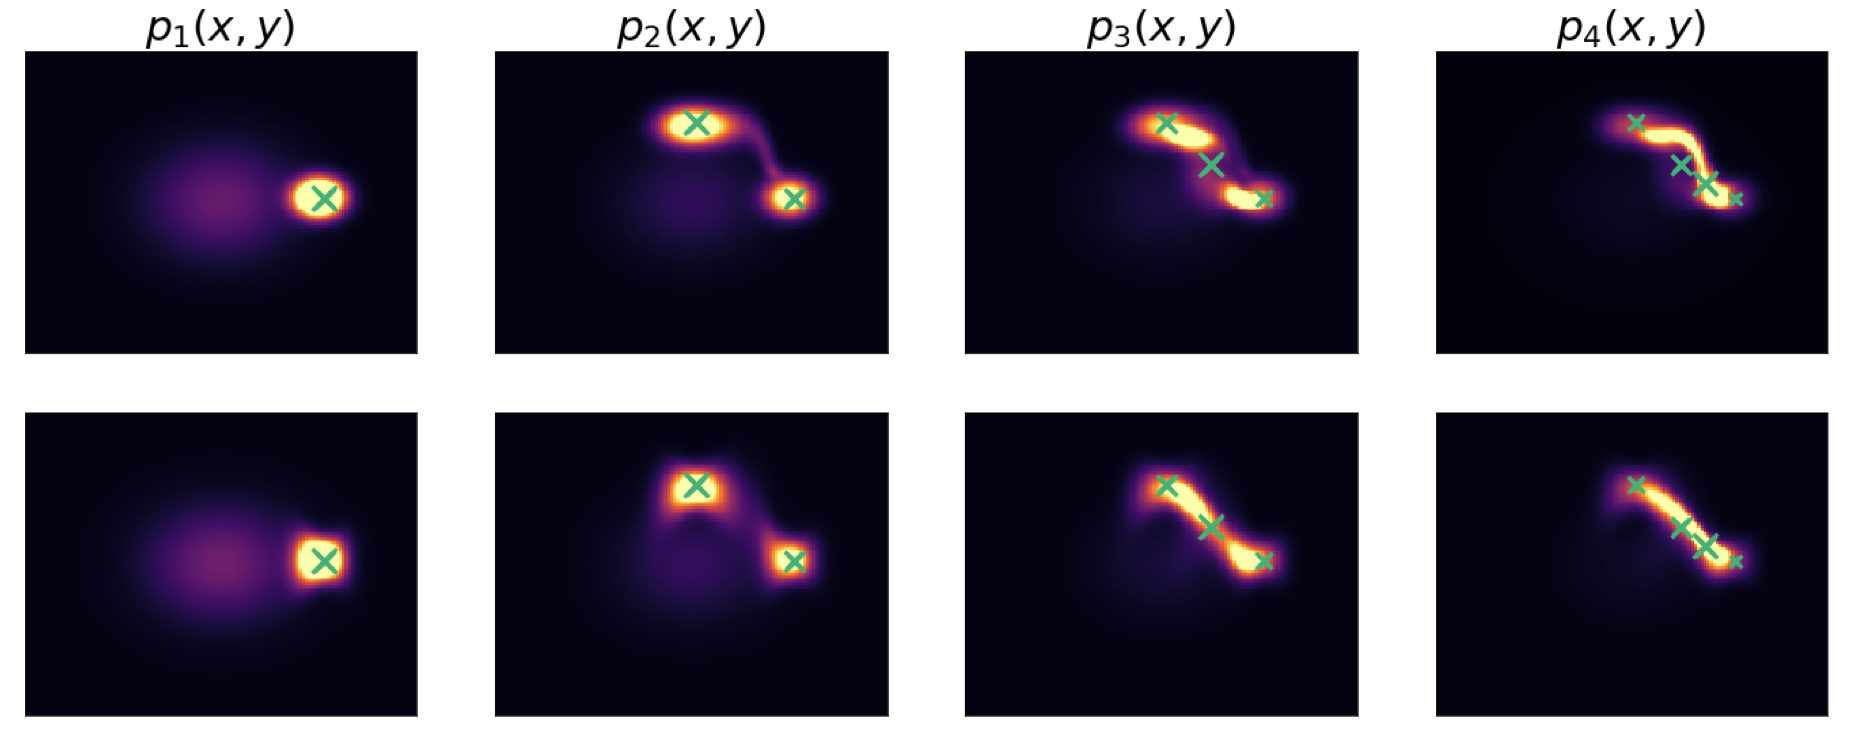
Bayesian methods are a popular choice for statistical inference in small-data regimes due to the regularization effect induced by the prior, which serves to counteract overfitting. In the context of density estimation, the standard nonparametric Bayesian approach is to target the posterior predictive of the Dirichlet process mixture model. In general, direct estimation of the posterior predictive is intractable and so methods typically resort to approximating the posterior distribution as an intermediate step. The recent development of quasi-Bayesian predictive copula updates, however, has made it possible to perform tractable predictive density estimation without the need for posterior approximation. Although these estimators are computationally appealing, they struggle on non-smooth data distributions. This is due to the comparatively restrictive form of the likelihood models from which the proposed copula updates were derived. To address this shortcoming, we consider a Bayesian nonparametric model with an autoregressive likelihood decomposition and a Gaussian process prior. While the predictive update of such a model is typically intractable, we derive a quasi-Bayesian update that achieves state-of-the-art results in small-data regimes.
Quasi-Bayesian nonparametric density estimation via autoregressive predictive updates
S. Ghalebikesabi, C. C. Holmes, E. Fong and B. Lehmann
Published: 04/08/2023
Published in:
The Thirty-Ninth Conference on Uncertainty in Artificial Intelligence (UAI 2023)
The Thirty-Ninth Conference on Uncertainty in Artificial Intelligence (UAI 2023)